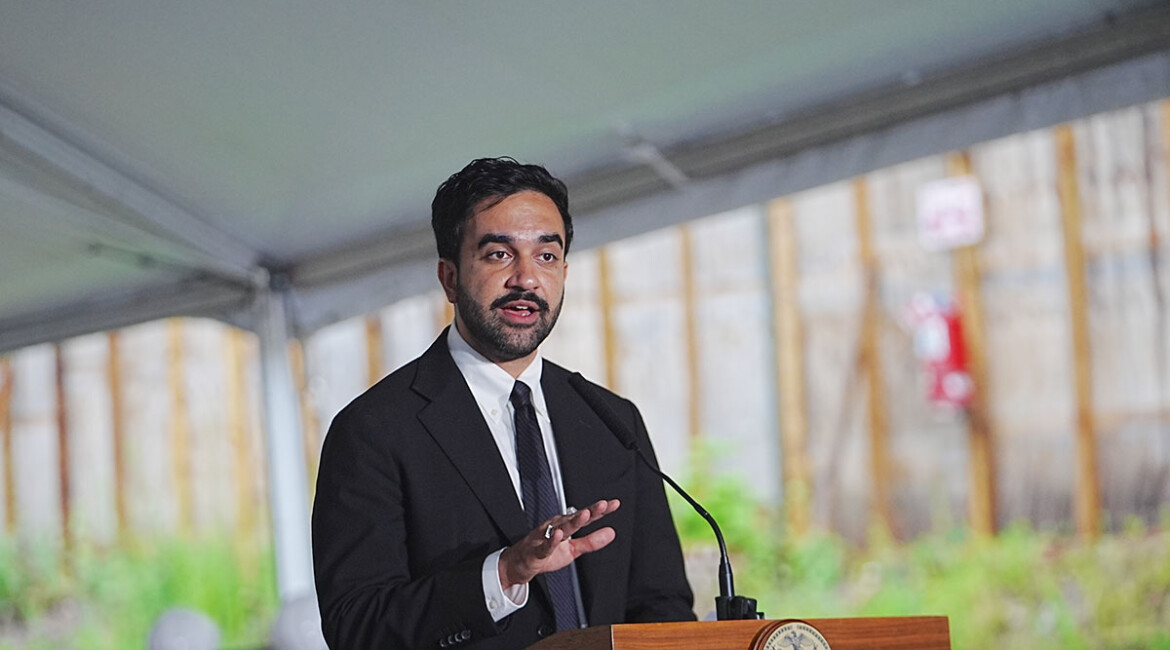
New York City Mayor Zohran Mamdani’s new tax on expensive second homes is facing a major legal challenge from casino mogul Steve Wynn and former U.S. Commerce Secretary Wilbur Ross, escalating a broader battle over one of the mayor’s signature revenue policies.
Wynn and Ross, both Florida residents who own luxury properties in New York City, filed a lawsuit against New York state arguing that the new pied-à-terre surcharge violates the state and federal constitutions.
The tax targets high-value properties that are not their owners’ primary residences. It applies to certain single-, two- and three-family homes valued above $5 million, while qualifying condominiums and cooperative apartments can face the surcharge at lower valuation thresholds.
New York officials expect the policy to generate approximately $500 million annually, helping the city address budget pressures and finance public services.
The plaintiffs, however, argue that the tax improperly discriminates against people who live outside New York City.
Ross and Wynn contend that nonresident property owners already pay property taxes while generally using fewer city services than full-time residents. They also argue that nonresidents cannot vote for the local politicians responsible for policies affecting their New York properties.
Ross could owe approximately $83,500, while Wynn could face a bill exceeding $183,000.
Their lawsuit raises another important argument involving New York’s limits on property taxation.
State law restricts how much New York City can raise through property taxes relative to the value of taxable real estate. The plaintiffs allege that lawmakers attempted to circumvent those restrictions by characterizing the new levy as a “surcharge” rather than incorporating it into conventional property taxes.
New York officials reject those arguments.
Governor Kathy Hochul’s administration has said the state is prepared to defend the law, arguing that owners of multimillion-dollar secondary residences should contribute more toward the city where those nu properties are located.
Mamdani’s administration has similarly defended the policy as a way of generating additional revenue from wealthy property owners who maintain expensive residences in New York without paying city income taxes as full-time residents.
The constitutional lawsuit comes amid a separate legal dispute over how the city implemented the tax.
New York State Supreme Court Justice Wayne Ozzi ruled that the city improperly placed too much responsibility on homeowners to prove that their properties were primary residences. Approximately 17,000 homeowners had received notices indicating that they could owe the surcharge.
The city had also published a supplemental tax roll containing more than 900,000 properties potentially relevant to the process.
Ozzi ordered officials to remove that list, cancel the existing notices and use available tax information to make more individualized determinations about which properties actually qualify.
Importantly, the judge did not invalidate the pied-à-terre tax itself.
New York City appealed the ruling, triggering a temporary stay while the litigation continues.
The Wynn-Ross lawsuit therefore presents a more fundamental challenge. Instead of simply questioning the administrative process, it seeks to have the underlying tax declared unconstitutional.
The dispute highlights a broader policy question facing New York: how aggressively can the city tax extremely valuable second homes owned by people whose primary residences — and often their income-tax obligations — are elsewhere?
Supporters describe the surcharge as a way to make wealthy second-home owners contribute more toward city finances. Opponents argue that it unfairly singles out nonresidents and potentially violates constitutional and statutory protections.
Those competing arguments will now move from New York’s political arena into its courts.
The outcome could determine not only whether New York can collect hundreds of millions of dollars from luxury second homes, but also how far state and city governments can go when designing taxes specifically aimed at wealthy nonresident property owners.